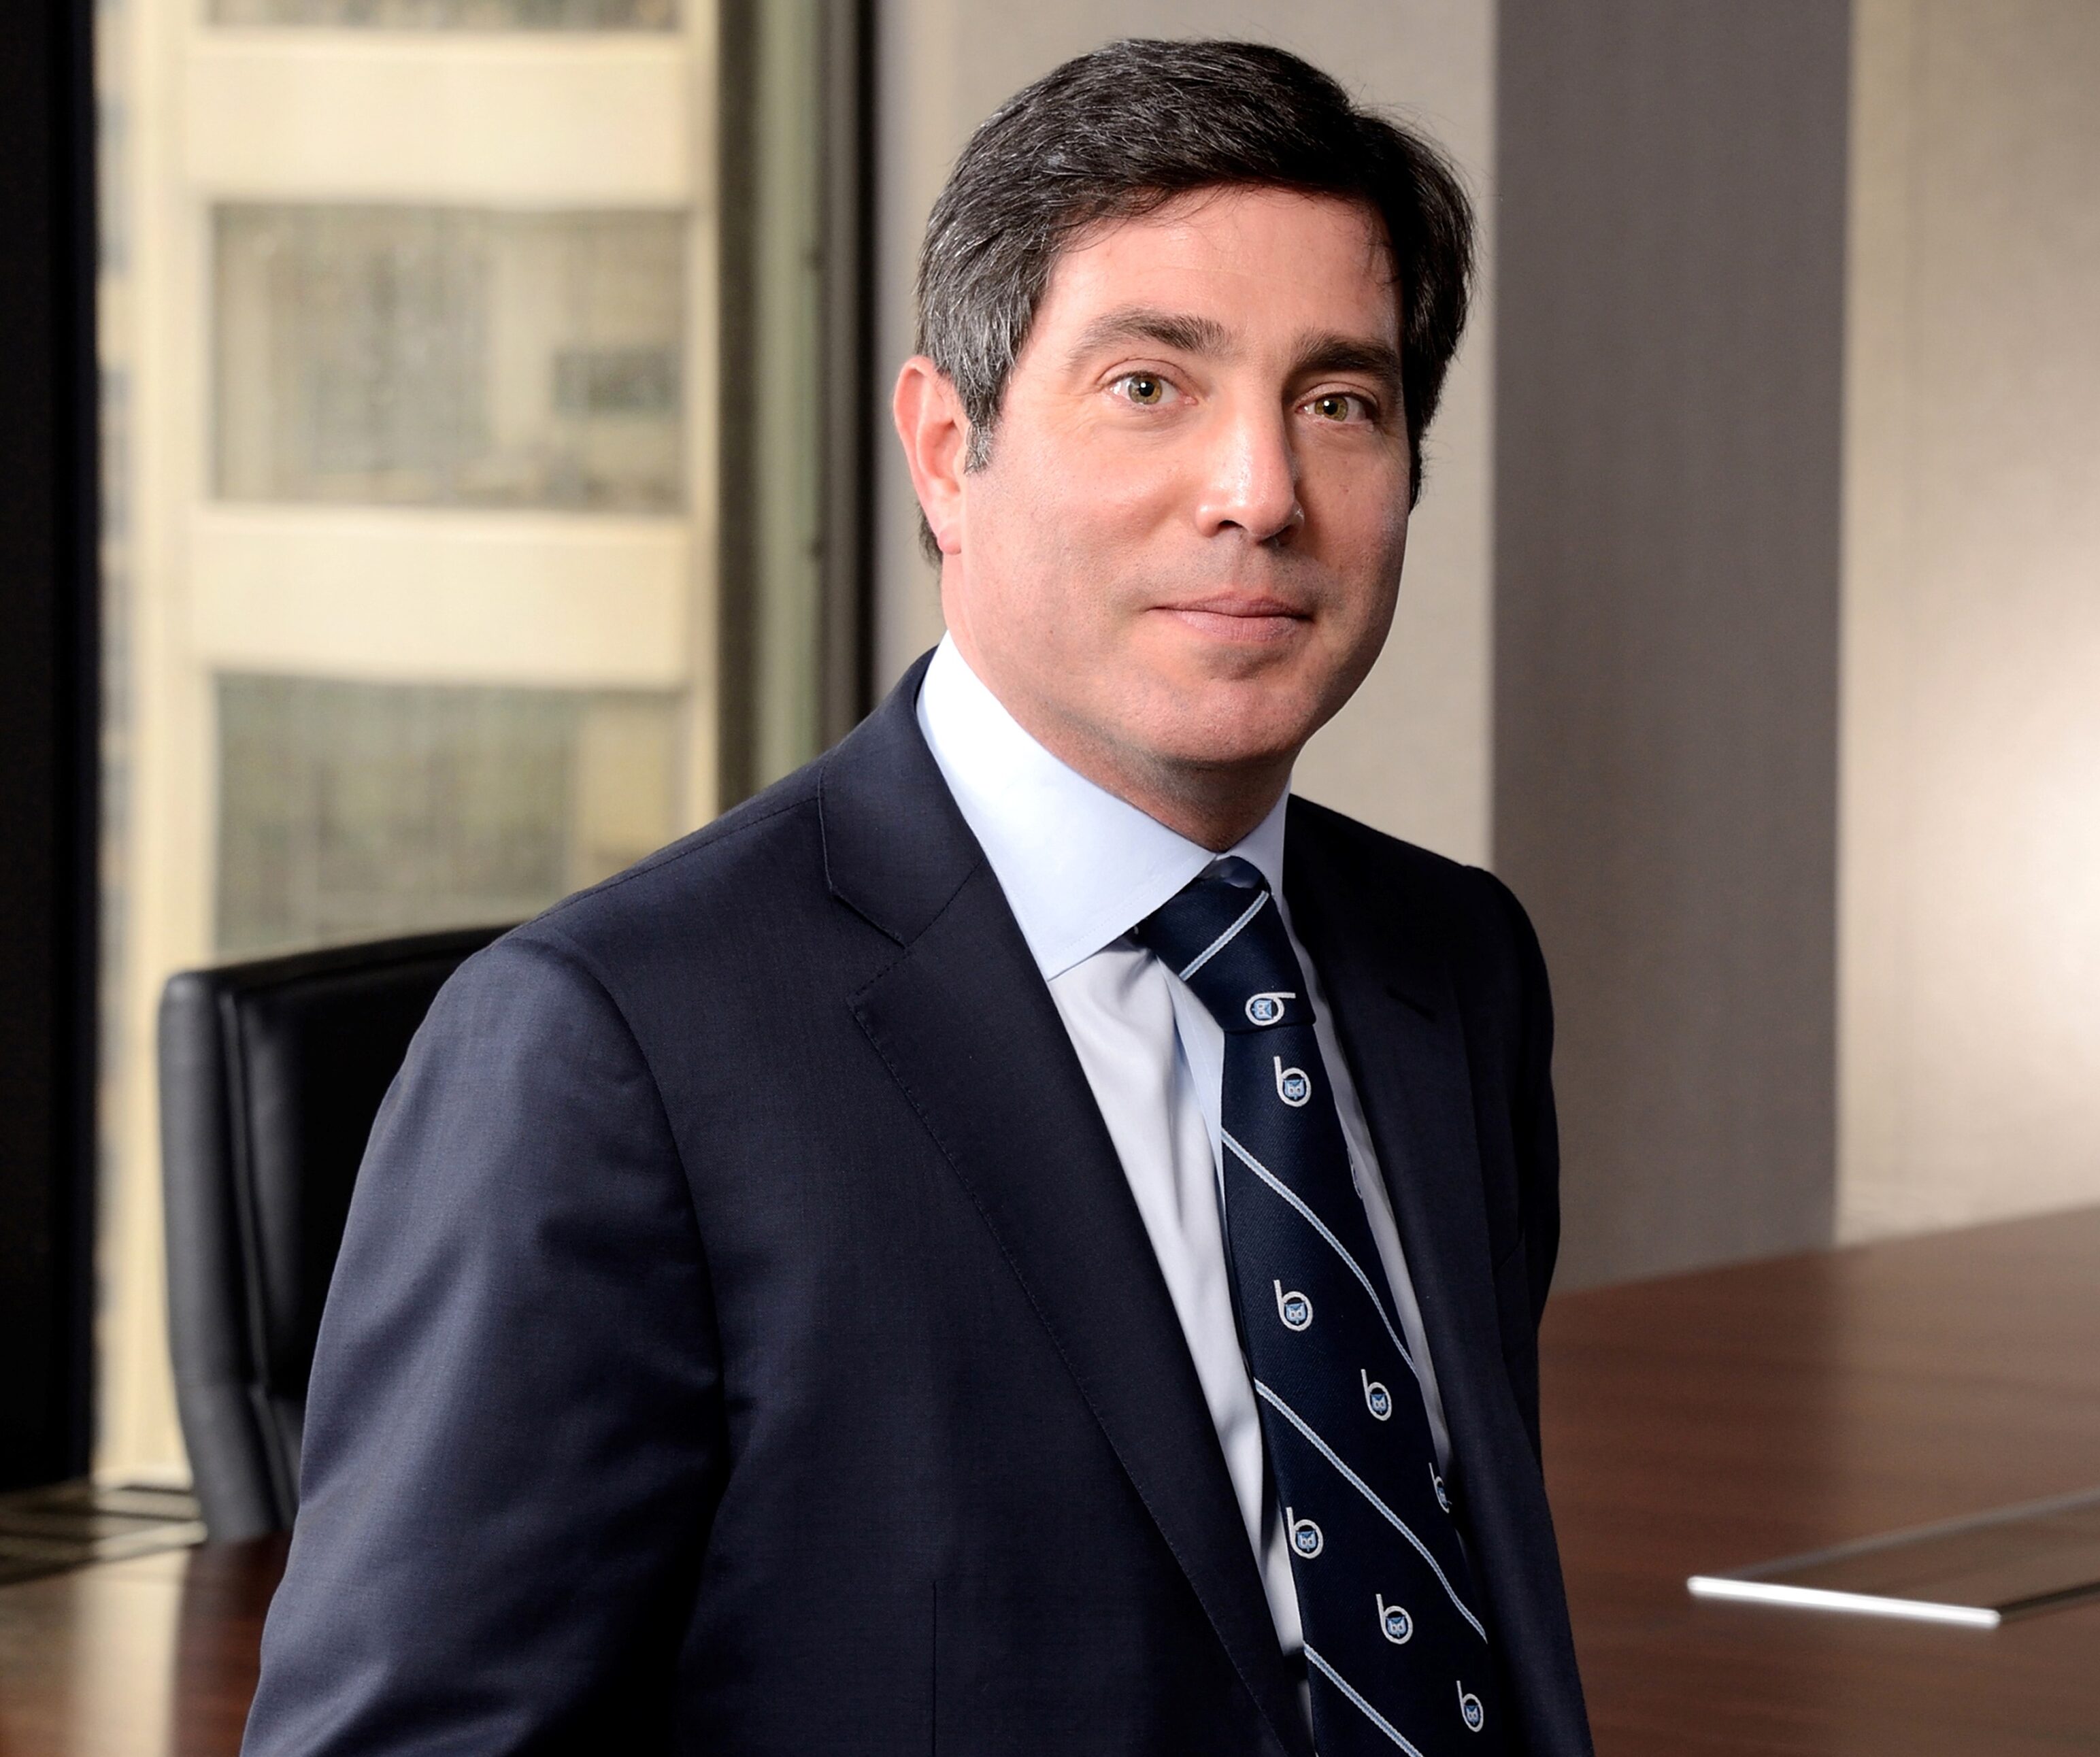
W.R. Berkley Corp. Chairman, President and CEO W. Robert Berkley, Jr. chose the third quarter of 2026 to enlighten analysts on the insurer’s journey parallel to society’s breakneck adoption of technological advances and its effect on the economy.
“My colleagues many, many years ago recognized the importance of data and how that role was going to become ever more greater,” he said in his opening remarks during a conference call to discuss Q3 earnings. “We have been on a data journey for many, many years at this stage. And fortunately for us, we are reasonably well positioned as we see many of the technology tools that are being brought to bear, AI-related in particular. Data is the fuel that drives those engines.”
Initially, artificial intelligence brought speed to the specialty insurer’s underwriting and claims, Berkley explained.
“While we are making our way well up that mountain, the next mountain that is before us is not just the benefits of speed, but the insights that we will be enjoying or further insights that we’ll be enjoying as it relates to decision-making,” he said. Insurance intake efficiency has improved “to the tune of 20%-plus.”
Additionally, in claims, Berkley said more than 50% are settling for $5,000 or less, which “would invite the idea that we should be able to have a lower and lower human touch when it comes to this,” Berkley said.
Related: WR Berkley Reports Q3 Net Income Decrease, Operating Income Up
Berkley said he thinks many perceptions related to the application of AI impact white-collar labor, but he sees some influence on the rest of the labor force, namely with robotics. This could eventually impact the workers’ compensation line.
“The labor force in this country and around the world is going to be a challenged as to how quickly we can retool people’s skill sets,” he said. “And there are certain jobs that are going to go away, not just because of AI in an office environment, but robotics can play an ever-increasing role. We’ve seen it to a certain extent in manufacturing.”
In terms of AI liability exposure, Berkley said the insurer has worked “very diligently to make sure the exposure is identified, understood, controlled – and we’re getting paid for it.” The company does employ exclusionary language in policies when appropriate, he added.
“We think that is our responsibility. And some people may like it, some people may not. But ultimately, that’s part of our responsibility in managing capital,” he explained.
On the insurance market, as the insurer has remarked in the past, Berkley said directors & officers is “in the process of bottoming out.” Without going into detail, he added that “there are several pockets within the professional space that we find very attractive.”
For some time Berkley has also expressed a dissatisfaction in the casualty, reinsurance and property environment, and he said the insurer is “waiting with bated breath, not in a happy way, to see what happens at 1/1 and what will follow.
“That, in all likelihood, will prove to be a challenging time,” he said, adding that Berkley expects its reinsurance business to shrink at 10% rate.
The commercial property market, Berkley said, “is going to get uglier before it gets prettier.” Opportunities lies within liability-related lines.
Was this article valuable?
Here are more articles you may enjoy.
 Broad AI Exclusions in Insurance Policies Could Create Uncertainty, Marsh CEO Says
 All in the Family: Husband, Wife and Daughter Indicted for Insurance Fraud and Bribery
 World’s Largest Retirement Community Set to Borrow $180 Million for More Homes
 Reuters: DXC in Advanced Talks to Sell Insurance Software Unit for $2.4 Billion