The UK’s accounting watchdog is proposing new rules for insurance companies to make sure actuaries factor in climate change risk.
“As the importance of climate change risks continues to grow it is critical that actuaries consider these risks in the course of their work,” Mark Babington, executive director of regulatory standards for the Financial Reporting Council, said in a statement Wednesday.
The move comes as regulators and insurers around the world get increasingly worried about climate risk after a rise in natural disasters. As many as 95% of insurance executives who took part in a BlackRock Inc. survey last year said that climate risk will have a major impact on how they build their portfolios over the next two years.
The FRC found that actuaries do a good job at taking into account more established risk areas, but do less well in considering non-traditional risks such as climate change, according to the statement.
The FRC’s consultation on the proposed changes closes on Sept. 7.
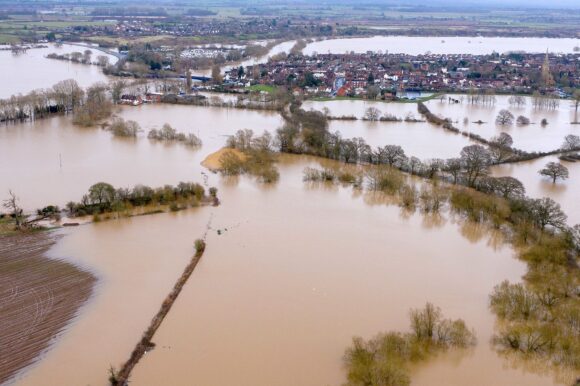
Photograph: Floodwaters surround Upton-upon-Seven, England, following Storm Dennis on Feb. 19, 2020. Photo credit: Christopher Furlong/Getty Images.
Topics Carriers Climate Change
Was this article valuable?
Here are more articles you may enjoy.
 Chubb CEO Greenberg: Industry Has to ‘Put Arms Around’ AI Liability
 PHP Security Flaws Highlight Potential Systemic Risk Aggregation for Cyber Insurers
 PwC Confirms Cybersecurity Incident Involving Employee Learning Records
 How Federal Ban on Intoxicating Hemp Products Will Reshape Risk, Coverage